What Nobody Tells Homeowners About Buying Their Next House
Owning a home once doesn't make the next purchase simpler; it makes it more layered. You're not just saving for a down payment anymore; you're managing an existing mortgage, home equity, and a sale that may or may not line up with your next purchase. Add in a market where Albuquerque homes sold in a median of just 14 days last month, and the timeline pressure is real. If you're planning to buy your next home in Albuquerque, here's what to sort out before you start touring houses.
What to Sort Out Before You Buy Your Next Home in Albuquerque
The good news: you have something first-time buyers don't: equity, credit history, and a track record as a homeowner. The trick is putting those to work in the right order so you can strategically navigate two mortgages, evaluate whether a bridge loan fits your plan, and ensure your pre-approval accurately reflects your real numbers.
If you’re a first-time homebuyer, make sure to check out our First Time Homebuyers Guide.
Check Your Home Equity First
Before anything else, get a realistic sense of what your current home is worth and how much equity you actually have to work with. A rough online estimate isn't enough here, since those tools miss local nuances like lot size, updates, or your specific neighborhood's recent sales. A comparative market analysis from a local agent gives you a number you can actually plan around, not just a ballpark.
Your equity typically becomes your down payment, your closing cost cushion, or both, so getting this number right before you buy your next home in Albuquerque shapes almost every decision that follows.
Decide: Sell First, Buy First, or Do Both at Once
This is the decision that trips up most move-up buyers, and there's no universally right answer, only trade-offs.
Sell first: you know your exact budget and avoid carrying two mortgages, but you may need to rent short-term or negotiate a rent-back if your next home isn't ready yet.
Buy first: you move once and avoid the scramble, but you'll need financing that accounts for your current mortgage, and possibly a bridge loan or home equity line of credit to cover the gap until your old home sells.
Do both at once: a contingent offer, buying subject to your current home selling, can work, but it's a harder sell to sellers in a competitive market and needs to be structured carefully by your agent.
With Albuquerque's detached-home inventory still sitting at about 2.5 months of supply, well below the 4 to 6 months that's considered balanced, sellers are still fielding strong interest on well-priced homes. That context matters when you're deciding how much flexibility you'll realistically get with a contingent offer.
Get Pre-Approved With Your Current Mortgage in the Picture
Pre-approval works differently the second time around because a lender has to factor in your existing mortgage payment alongside your new one, at least until your current home sells. Depending on the loan program, you may need documentation showing your home is under contract or has sold before your full new mortgage payment is excluded from your debt-to-income calculation.
Have these ready before you talk to a lender:
-
Two years of tax returns and W-2s or 1099s
Recent pay stubs and two to three months of bank statements
-
Your current mortgage statement, including payoff amount if you're selling
A list of other debts: auto loans, student loans, credit cards
-
Documentation of any additional income you want counted, such as rental income
Mortgage rates are part of this math too. The 30-year fixed rate averaged 6.71% as of early September 2026, according to Freddie Mac, with the 15-year fixed averaging 6.04%. A lender can show you exactly how your existing mortgage and a new one at current rates affect what you qualify for.
Line Up Your Down Payment and Closing Costs
If your equity is covering the down payment, you'll typically need it available in liquid form around the time of closing, not just on paper. Closing costs on top of that generally run 2% to 5% of the purchase price.
Repeat buyers sometimes assume down payment assistance is only for first-timers, but that's not universally true. New Mexico's MFA NextHome program is specifically built for repeat buyers, offering down payment assistance with higher income and purchase price limits than the state's first-time buyer programs. It's worth asking a participating lender whether you'd qualify before ruling it out.
Know What Today's Albuquerque Market Is Doing
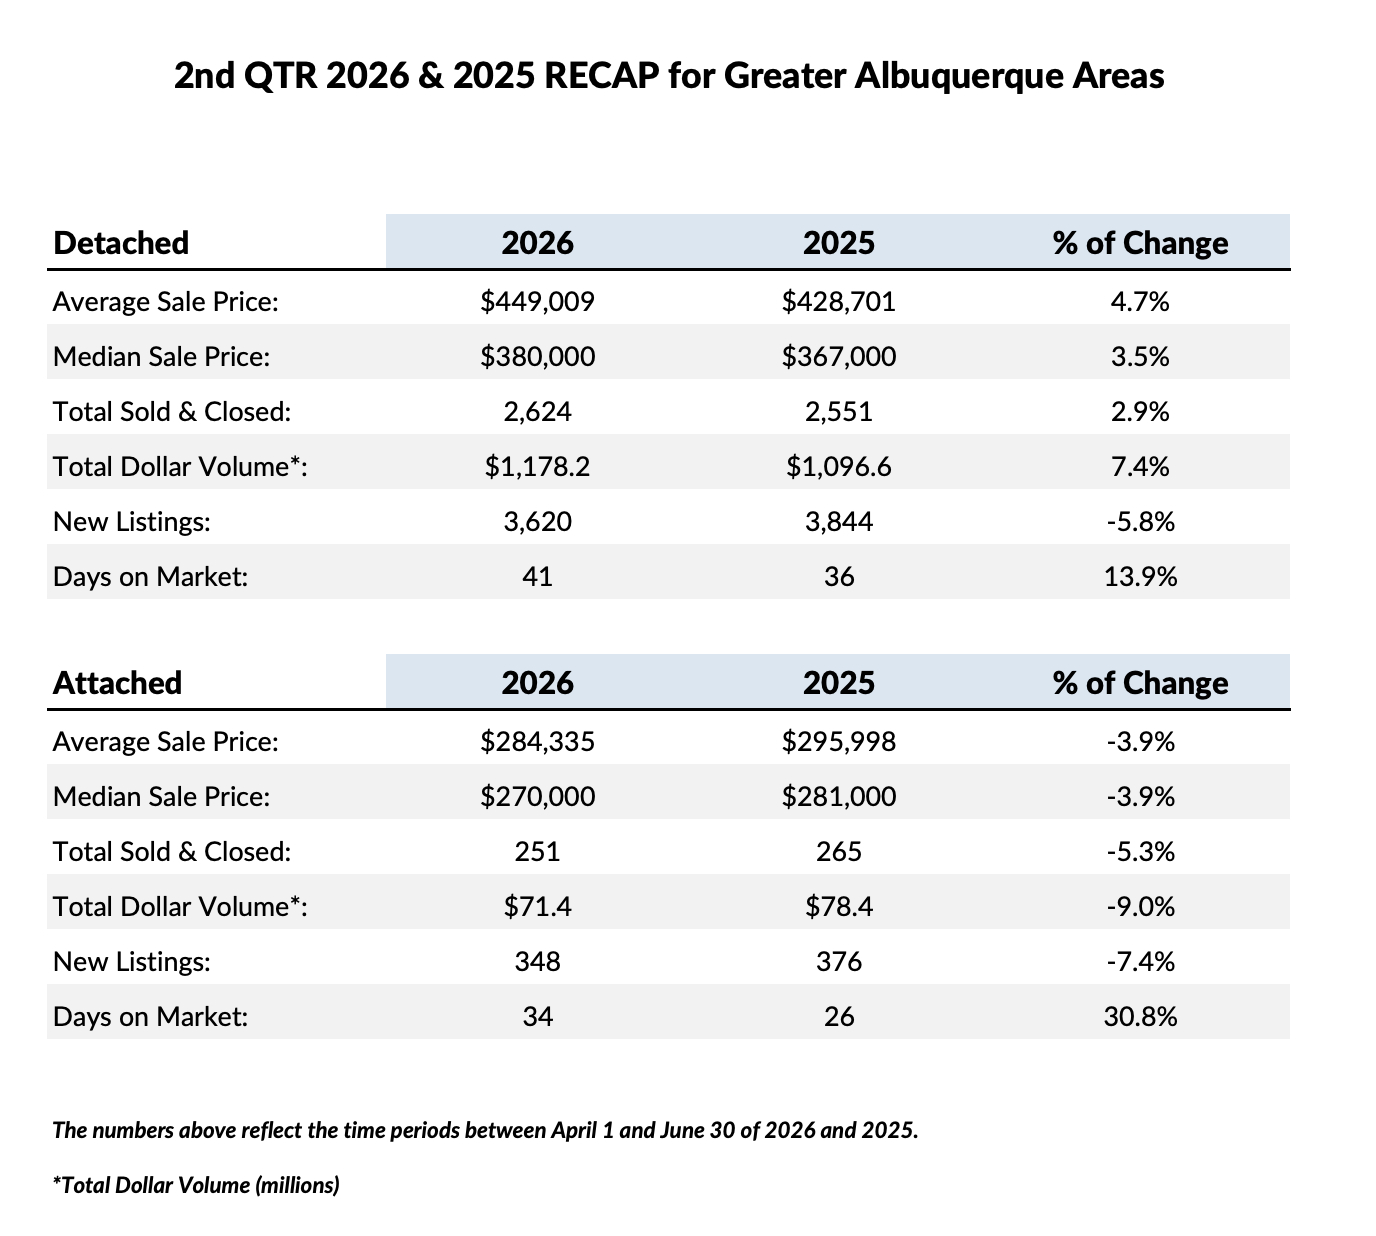
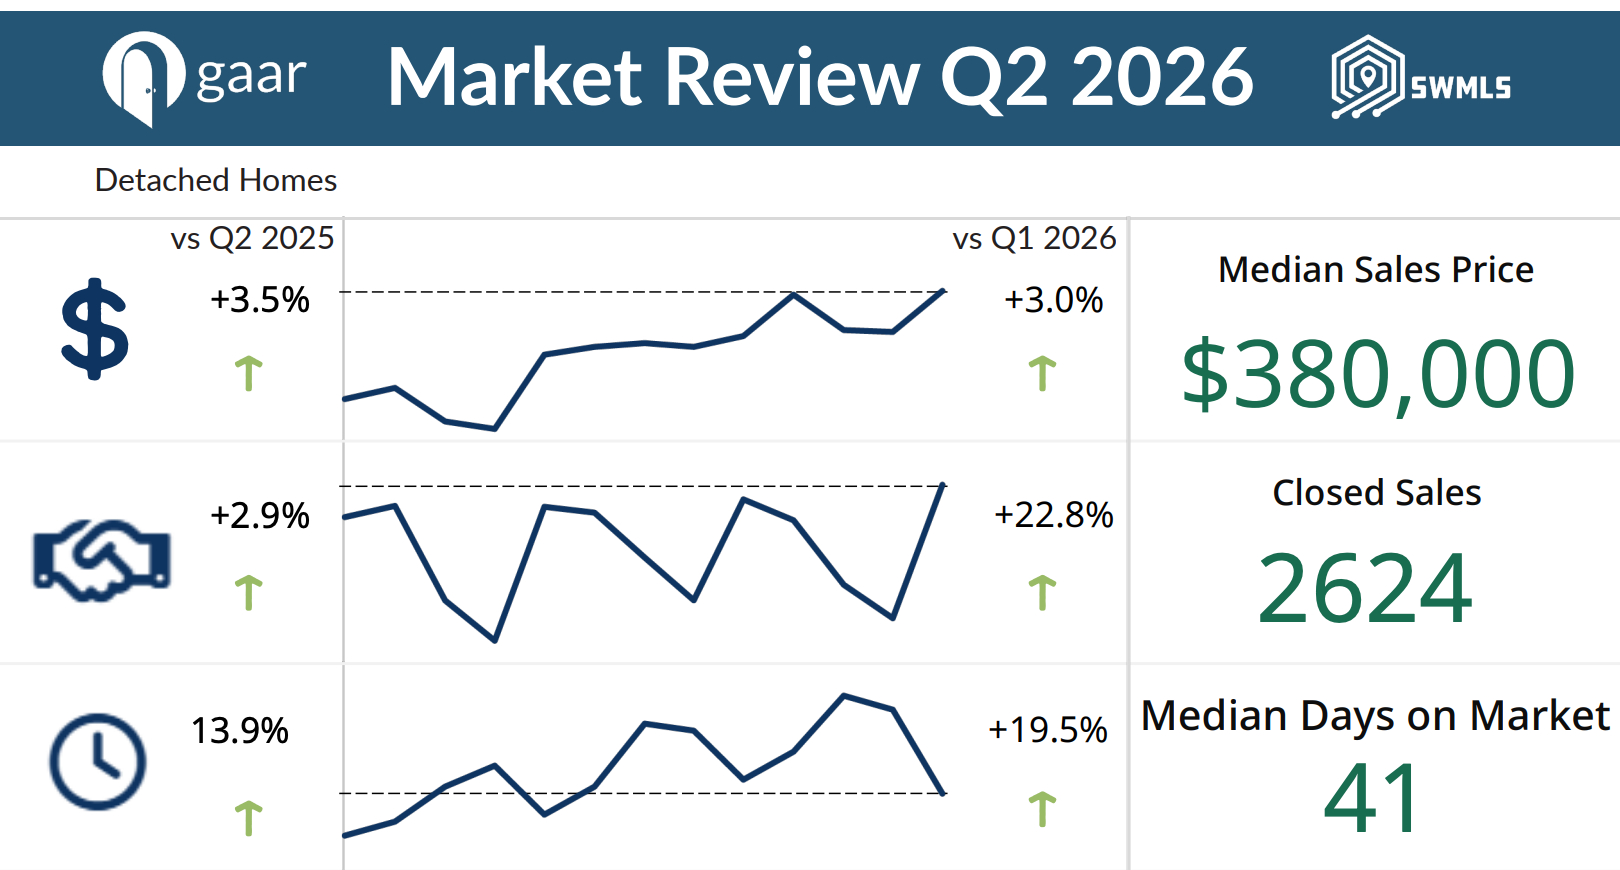
Timing your move effectively requires a clear view of current local real estate trends. Here is a snapshot of key metrics for Greater Albuquerque detached homes based on recent GAAR data:
-
Median Sales Price: $385,000
Median Days on Market: 14 days
-
Average Sale Price vs. List Price: Sellers received 98.9% of list price on average
Active Inventory Growth: Up 11.1% from the prior month, indicating more options coming onto the market
That combination, rising inventory but still-fast sales, is exactly why timing matters when you plan to buy your next home in Albuquerque. A home that sits at 14 median days on market doesn't leave much room for indecision once you find the right one.
Buying again isn't harder because you know less; it's harder because there's more to coordinate. Get your equity, your pre-approval, and your sell-or-buy-first strategy lined up before you buy your next home in Albuquerque, and the rest of the process moves a lot more smoothly.
Have questions about your equity or the current market? Schedule a quick chat with us to get your next steps sorted.