If you caught the headlines this week, you already know mortgage rates climbed. The 30-year fixed hit 6.95% on September 17, its highest level since January 2025 and the fourth weekly increase in a row. That matters for your Albuquerque mortgage payment, no question. But the local picture is more encouraging, and the real numbers are worth a look before you decide anything.
Why Rates Went Up This Month
The short version: the Federal Reserve raised its benchmark rate, and the 10-year Treasury yield has been sitting near 5%. Mortgage rates follow that 10-year yield more closely than they follow the Fed itself, so when bond yields rise, lenders reprice quickly.
Here's how the average 30-year fixed has moved, according to Freddie Mac's weekly survey:
Early March 2026: 6.00%
-
August 27: 6.66%
September 3: 6.71%
-
September 10: 6.76%
September 17: 6.95%
-
One year ago: 6.26%
One thing to keep in mind: that weekly average assumes 20% down and excellent credit. Your actual quote depends on your credit score, loan type, down payment, and whether you pay points, so it could land above or below the headline number.
What Your Albuquerque Mortgage Payment Looks Like at 6.95%
Let's plug in a real local number. GAAR's August report put the median sales price for a detached home in the Albuquerque metro at $385,000. With 20% down, that's a $308,000 loan on a 30-year fixed. Here's how the monthly principal and interest compares:
-
At 6.00% (early March): about $1,847 a month
At 6.26% (a year ago): about $1,898 a month
-
At 6.95% (today): about $2,039 a month
That's roughly $192 more per month than this spring, or about $2,300 a year. These figures cover principal and interest only. Property taxes, homeowners insurance, and any HOA dues get added on top, and those vary quite a bit from the Northeast Heights to the West Side.
The Local Market Is Quietly Working in Buyers' Favor
Here's the part national coverage misses. Albuquerque's market has been loosening all summer, and higher rates tend to thin out the buyer pool even further. GAAR's August numbers for detached homes tell the story:
Median sales price: $385,000
-
Median days on market: 18, up 28.6% from a year ago
Active inventory: 2,285 homes
-
Months supply of inventory: 3.1, up from a year ago
Percent of list price received: 98.7%
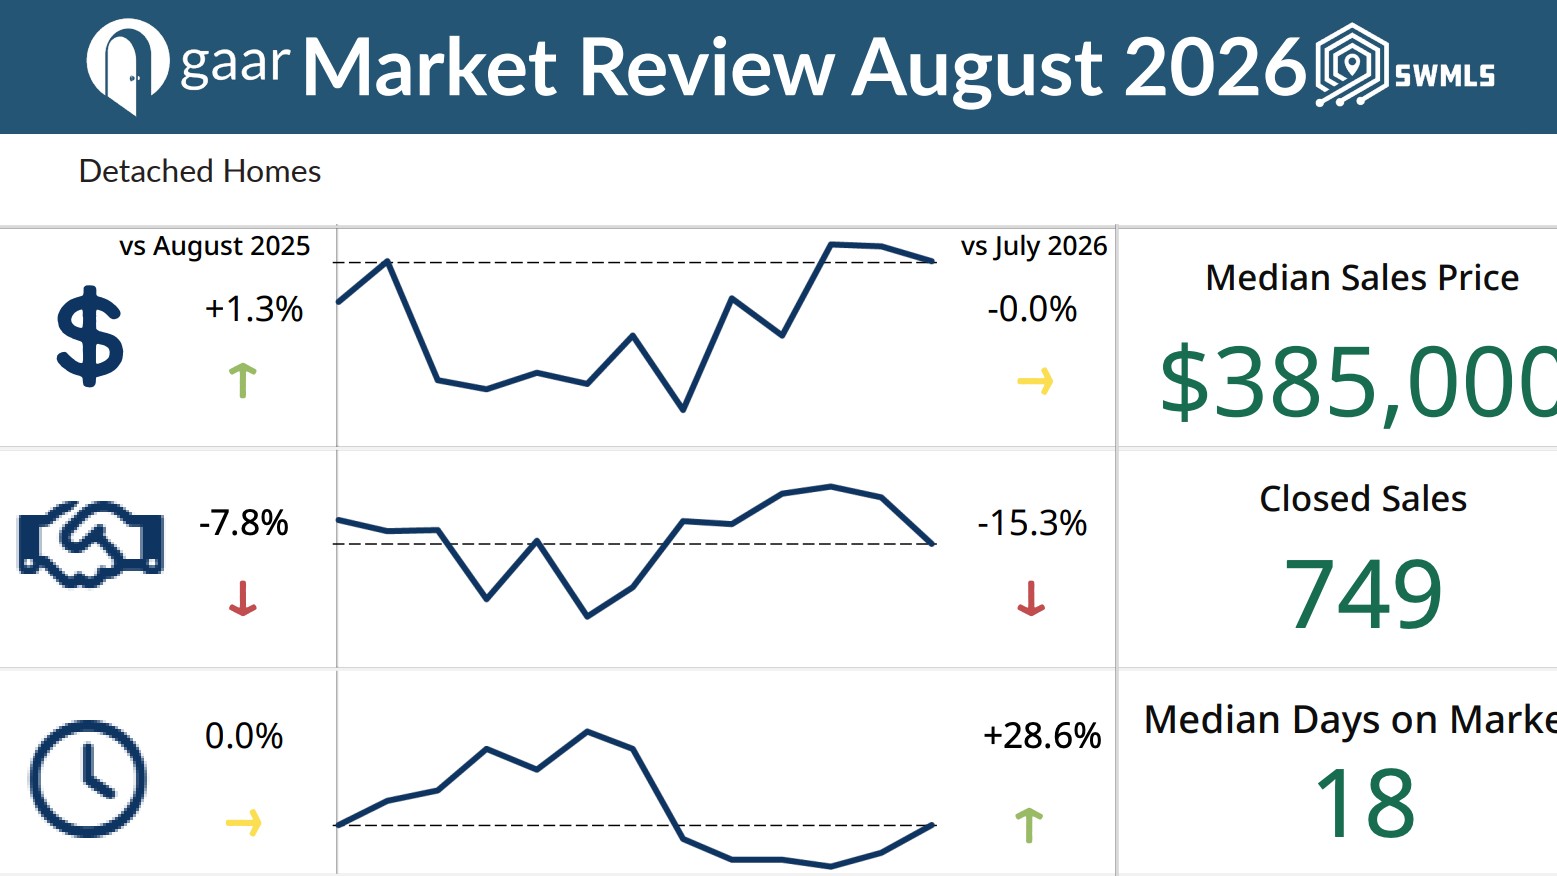
Source: Greater Albuquerque Association of REALTORS® / Southwest MLS, August 2026. Data deemed reliable but not guaranteed.
Put simply, buyers have more choices, more time to decide, and sellers who are more open to a conversation than they were in the spring. Supply is still below what NAR considers a balanced market, so well-priced homes in popular Albuquerque neighborhoods still move fast. But plenty of listings are sitting long enough that negotiating is realistic again.
Check out up-to-date numbers in our August 2026 Market Update.
Smart Ways to Lower Your Payment Right Now
The rate is only one lever. There are several others you can actually pull.
Ask for concessions, not just a lower price
A $10,000 price reduction trims about $53 from your monthly payment. That same $10,000 as a seller credit toward a rate buydown can sometimes lower your payment by more, depending on how your lender prices it. Ask your lender to run both scenarios side by side before you write an offer.
Consider a temporary buydown
A 2-1 buydown lowers your rate by two points in year one and one point in year two before settling at the full rate. Sellers and builders sometimes fund these. It can give you breathing room in the first couple of years; just make sure the full-rate payment fits your budget comfortably on its own.
Refresh your pre-approval
A pre-approval issued back in the spring was based on a lower rate. If yours is more than a couple of months old, ask your lender to update it so you know exactly what your Albuquerque mortgage payment looks like at current pricing. A fresh letter also shows sellers you're serious, which carries real weight when you're asking for concessions.
Check New Mexico MFA programs
New Mexico MFA offers down payment and closing cost assistance for eligible buyers, including repeat buyers in some programs. Income and purchase price limits apply, so it's worth checking early in the process.
Should You Wait for Rates to Come Back Down?
It's the question everyone's asking, and the honest answer is that nobody can reliably predict where rates go next. Waiting comes with its own trade-offs. If rates ease, more buyers tend to jump back in, and the negotiating room you have today could shrink.
A better approach is to focus on what you can control. Figure out an Albuquerque mortgage payment you're comfortable with at today's rate, not a hoped-for future rate. If the right home fits that number, you're in a solid spot.
The Bottom Line for ABQ Buyers
Rates went up, and that shows up in your Albuquerque mortgage payment. But local inventory is up, homes are taking longer to sell, and buyers have more leverage than they've had in a while. Knowing your real numbers is the best way to decide whether now is your moment.
Want help running the math on a specific home or neighborhood? Our team knows this market street by street, and we're happy to walk through your options. Contact us to get started.
Payment examples are for illustration only and do not represent a loan offer or rate guarantee. Talk with a licensed lender for a personalized quote.