When mortgage rates rise, the monthly payment on the same house rises with them. This week, the average 30-year rate crossed 7% for the first time since January 2025. On a median-priced Albuquerque home, that works out to roughly $168 more a month in principal and interest than a buyer would have paid a year ago, when rates averaged 6.30%.
For sellers, that raises a fair question: do I need to drop my price? Not necessarily, and seller concessions in Albuquerque are a big reason why.
A seller concession is money the seller agrees to put toward the buyer's closing costs, like lender fees or lowering the buyer's interest rate. Used well, it can do more for a buyer's monthly payment than a price cut of the same dollar amount. Here's how it works, what the latest local numbers say, and how to decide which approach fits your home.
What the Latest GAAR Numbers Say About Negotiating Room
Albuquerque is still a seller's market. It's just a calmer one than it was a year ago. Here's where detached homes landed in August, according to GAAR's Southwest MLS data:
Median sales price: $385,000, up 1.3% year over year
-
Median days on market: 18, up 28.6% from August 2025
Active inventory: 2,285 homes, up 3.2% year over year
-
Months supply of inventory: 3.1 months, still below the 5 to 6 months generally considered balanced
Percent of list price received: 98.7%
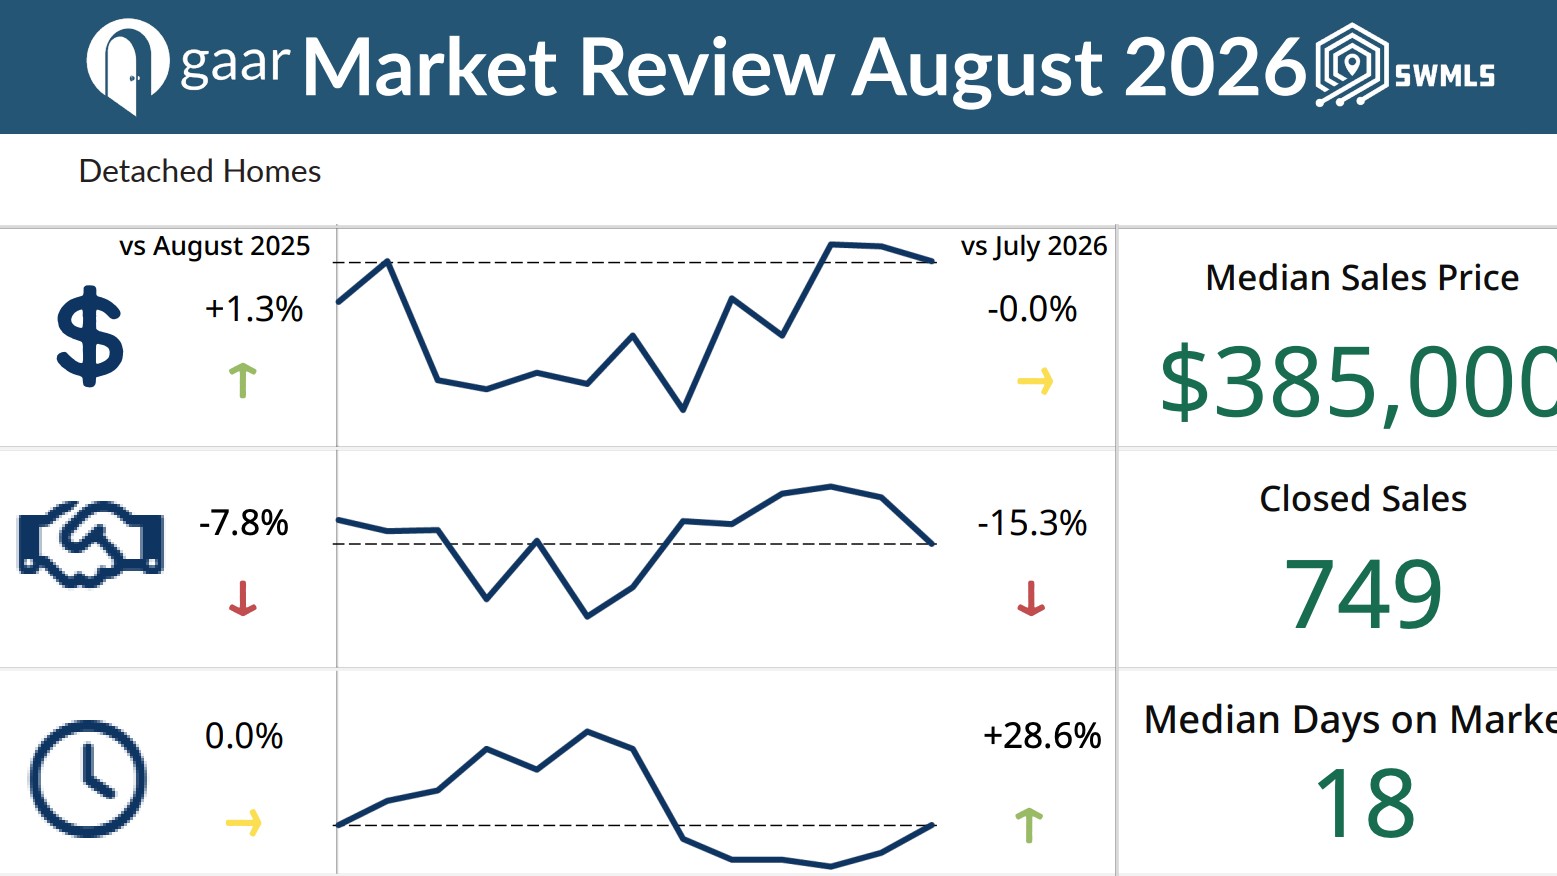
Prices are holding, which is good news for sellers. But buyers have more homes to compare and a little more time to decide. Add Freddie Mac's latest 30-year average of 7.03%, up for five straight weeks, and the homes that stand out are the ones that make the monthly payment easier to swallow. That's exactly where seller concessions in Albuquerque come in.
Seller Concessions in Albuquerque, Explained
On paper, a concession shows up as a credit on the closing statement rather than a lower sales price. Depending on the loan program, that credit can cover closing costs, prepaid items like property taxes and homeowners insurance, and a rate buydown, which means paying upfront so the buyer gets a lower interest rate and a smaller monthly payment.
There are a few firm rules. Concessions can't be used for the buyer's down payment; they can't exceed the buyer's actual eligible costs, and the buyer can't walk away with the extra as cash. Every dollar also has to be disclosed to the lender and written into the purchase agreement. Side deals that skip that step can put the whole loan at risk.
How Much Can a Seller Contribute?
Before you offer seller concessions in Albuquerque, know that each loan program caps what the seller and other interested parties can put in. These are the standard limits, based on the sales price or appraised value, whichever is lower:
Conventional, primary home: 3% with less than 10% down, 6% with 10% to 25% down, and 9% with more than 25% down
-
Conventional, investment property: 2%
FHA: 6%
-
VA: normal closing costs, plus up to 4% in additional concessions such as a buydown or prepaid items. See our Albuquerque VA loans guide for more information.
USDA: 6%
On Albuquerque's $385,000 median, that's $11,550 at 3% and $23,100 at 6%. Kirtland Air Force Base and a large veteran community make VA buyers a big part of our local market, so it pays to know how that program treats credits. Your buyer's lender always has the final word on what's allowed for their specific loan.
The Math: Same Money, Very Different Results
Here's where it gets interesting. Take a $385,000 home and a buyer putting 10% down on a conventional loan at 7.03%. Their principal and interest payment is about $2,312 a month.
Option 1: A 2-1 temporary buydown
The seller funds a credit that lowers the buyer's rate by two points in year one and one point in year two.
On this loan, that costs roughly $8,087. The buyer pays about $1,866 a month in year one, saving $446, and about $2,084 in year two, saving $228. From year three on, the payment returns to the full rate.
Option 2: An $8,087 price cut
Same money off the sales price. The buyer's payment drops to about $2,264, a savings of only $49 a month.
That's the whole case in one comparison. For a buyer watching rates climb, $446 a month in year one feels a lot bigger than $49. And for the seller, the contract price stays higher, which can matter for how your sale shows up in the comparable sales data future appraisals rely on.
Temporary Buydown or Permanent Buydown?
A temporary buydown, like the 2-1 above, front-loads the relief. It's a strong fit for buyers who expect their income to grow, or who hope to refinance if rates ease. It's a bridge, not a guarantee, and no one can promise where rates are headed.
A permanent buydown uses discount points to lower the rate for the life of the loan. Pricing varies by lender and changes daily, but one point, equal to 1% of the loan amount, often lowers the rate by around a quarter point. On our example loan, two points cost about $6,930 and would trim the payment by roughly $115 a month, every month. Buyers who plan to stay put for many years tend to value that steady savings.
When a Price Reduction Still Makes Sense
Concessions aren't a cure for everything. If a home is priced above what recent sales support, a credit won't fix it, because the appraisal still has to meet the contract price. In that case, getting the price right is the first move.
Price drops also have a marketing effect that credits don't. A reduction can push your home into a new search range and put it in front of buyers who filtered it out. And a lower price means a smaller loan, which helps buyers who care most about total cost over time. The right answer depends on your home, your price point, and who's actually touring it.
How to Use Seller Concessions in Albuquerque the Smart Way
The strongest strategy usually starts with a well-priced home, then uses a credit as a closing tool rather than a crutch. Offering seller concessions in Albuquerque works best when you're specific. Instead of a vague "seller will help with costs," consider framing it as a credit the buyer can put toward a rate buydown or closing costs, and let your agent share an example payment from a lender so buyers can see the difference.
Timing matters too. Some sellers hold concessions in reserve for negotiation, or to respond to inspection requests instead of handling repairs before closing. Others lead with them when a listing needs a fresh reason to get noticed. With homes sitting a bit longer this fall, that decision deserves a real conversation with your listing agent and a trusted local lender before you change a thing.
The Bottom Line for ABQ Sellers
Seven-percent rates change what buyers are shopping for. They're not just comparing houses; they're comparing payments. A price cut is the reflex, but seller concessions in Albuquerque can often deliver more relief per dollar while protecting your sales price. The key is running the numbers on your home and your likely buyer, not someone else's.
Thinking about listing this fall, or wondering if your current listing needs a new approach? The Better with Baron team can walk through your options with real local data.
Market data source: Greater Albuquerque Association of REALTORS® / Southwest MLS, August 2026, detached single-family homes. Information deemed reliable but not guaranteed. Mortgage rate data: Freddie Mac Primary Mortgage Market Survey, September 24, 2026. Payment examples are estimates for illustration only, include principal and interest only, and are not a loan offer or commitment to lend. Concession limits and buydown eligibility vary by loan program and lender; consult a licensed mortgage professional for guidance on your situation.